
Busier Than Ever, Earning Less: Set a Margin Floor Before You Sign
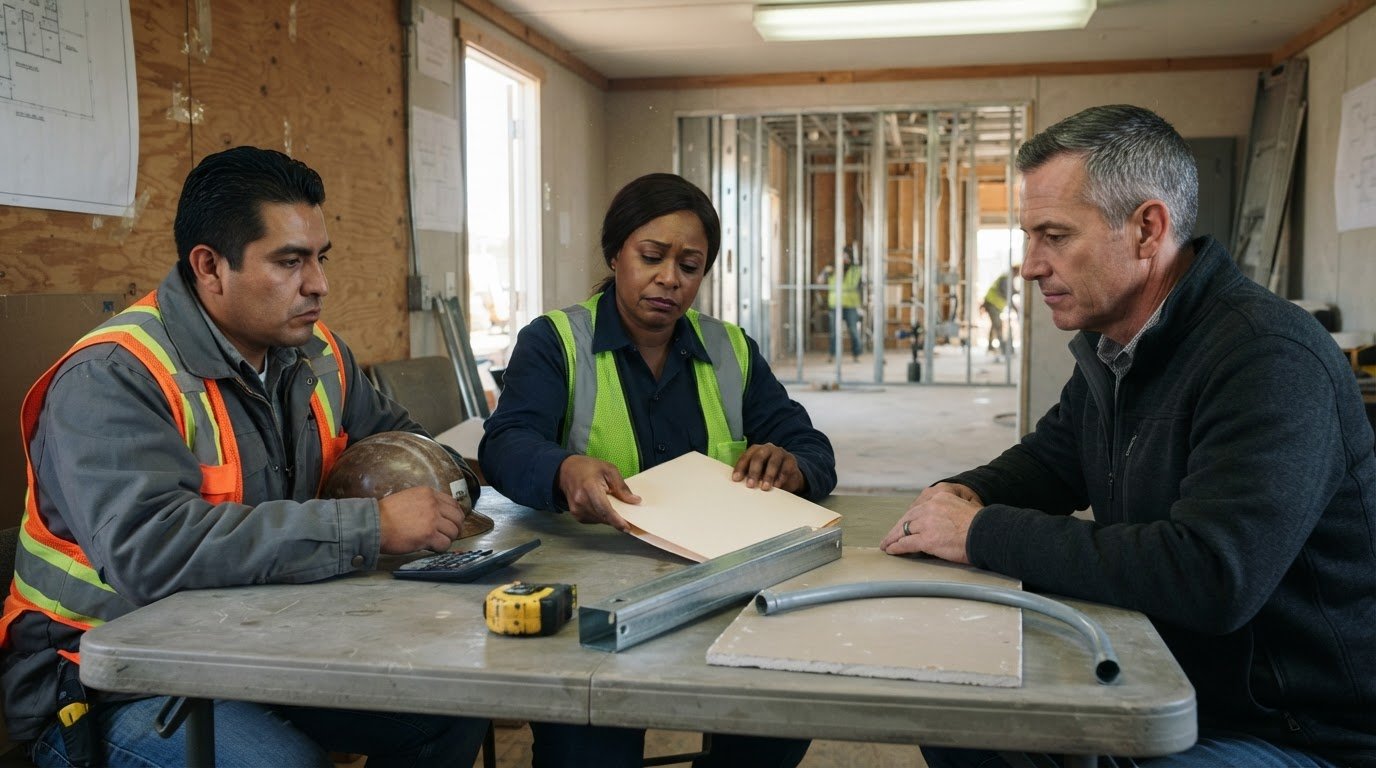
More work can leave a construction business less profitable. The practical response to being busier than ever and earning less is to set a minimum gross margin before you sign, based on overhead and the profit you need. For example, a contractor expecting $2.4 million in annual revenue, with $480,000 in overhead and a $192,000 target net profit, needs a 28% gross margin.
Revenue growth can look like progress while rising costs or discounts quietly reduce profit. The top line matters, but it does not show whether each project covers its share of overhead or meets your target.
This article explains how to assess construction margins, set a practical floor, and weigh discounts against the work they require. It also shows how customer- and product-level analysis can reveal where profit is made and where activity consumes it.
Key Takeaways
• Assess whether growth is improving gross and net profit, not just revenue, by comparing results across consistent periods.
• Set a margin floor that accounts for overhead and your target profit before committing to a project.
• Evaluate discounts against their effect on contribution and the additional volume or improved payment terms they need to justify.
• Identify which customers and products generate profit by accounting for the work and costs they consume.
Table of Contents
• Construction Profit Margins: Is Your Growth Making Money?
• Trading discounts for longer terms, more volume, or faster payment
• Customer- and product-level margin analysis
Construction Profit Margins: Is Your Growth Making Money?
Revenue growth matters when it produces sustainable profit. U.S. tax, labor, and contract requirements can affect job costs, timing, and obligations, so account for applicable requirements in each bid. Track labor, materials, overhead, travel, and payment fees separately to understand how direct costs and operating expenses affect margin.
Gross, Contribution, and Operating Margins
Gross margin is gross profit divided by revenue after direct job costs. Contribution margin subtracts variable costs and shows what remains for fixed costs. Operating margin measures operating profit against revenue after overhead. Separating these measures shows whether a project covers delivery costs, supports operations, and contributes to profit.
Construction Margin Benchmarks
NYU Stern professor Aswath Damodaran’s January 2026 data showed 15.46% gross margin and 5.94% net margin for 48 U.S. listed engineering and construction companies. Its 30 homebuilders recorded 22.70% gross and 9.47% net margins. Paar Melis’s report on 2024 auto repair shop financials found top-decile net profit of 19.9%, versus a 1.3% net loss in the bottom decile. These benchmarks describe different businesses, not automatic targets.
Growth and Margin Erosion
Growth can increase gross profit while reducing the profit left after overhead. In one contractor example, revenue rose from $1,600,000 to $2,200,000, and gross profit increased from $512,000 to $594,000. Yet gross margin fell from 32% to 27%, overhead climbed from $380,000 to $520,000, and net profit dropped from $132,000 to $74,000. The net margin declined from 8.3% to 3.4%. Added workload, hiring, or price concessions can make bigger revenue less profitable.
Setting an Operating Margin Target
Set a target by relating expected revenue to overhead and the profit the business needs to retain. In an illustrative contractor example, $2.4 million in expected annual revenue, $480,000 in overhead, and a $192,000 target net profit require a 28% gross margin. The target net profit equals 8% of revenue. Use this calculation to define a bid floor, then assess each project against its direct costs and its contribution to company-wide expenses. Many contractors rely on dedicated estimating tools such as Best Bid to accurately model these direct costs and protect their target margins on every proposal.
Trading discounts for longer terms, more volume, or faster payment
Treat a discount as a trade, not a default: link each price concession to volume, faster payment, or lower delivery costs. The principle behind “Busier Than Ever, Earning Less: Set a Margin Floor Before You Sign” is to protect your return before agreeing on a price. Accurate costing and clear contract terms help prevent concessions from eroding the margin floor.
Break-Even Effects of Price Changes
Break-even analysis shows how a price change alters the sales volume needed to cover fixed costs. At a $100 price and $60 variable cost, contribution is $40 per unit; monthly fixed costs of $120,000 require 3,000 units to break even. Discounting the price to $90 cuts contribution to $30, lifting break-even volume to 4,000 units, a 33% increase. A five-point price increase can withstand an 11% customer loss before it negatively affects profit. Divide fixed costs by contribution per unit to compare the tradeoffs.
Minimum Margin and Discount Thresholds
A discount threshold is the limit that protects the minimum contribution needed from each order. Set it by costing labor, materials, variable delivery expenses, and overhead allocation before approving a concession. A 10-point discount on a service with a 40% gross margin requires one-third more business to break even. Longer payment terms also tie up working capital; some customers in the example paid on 90-day terms. Applying the “Busier Than Ever, Earning Less: Set a Margin Floor Before You Sign” principle means trading concessions only for measurable value, such as committed volume, faster payment, or reduced servicing effort. Track credits, including uncredited cores where relevant, alongside cost increases.
Contract Terms That Protect Margins
Clear contract terms make scope, pricing, and changes visible before work proceeds. Define included work, exclusions, how change orders are documented and priced, and when written approval is required. Set out how cost increases are handled and specify payment milestones and due dates. These terms support consistent costing; they don’t replace reviewing each change’s impact on labor, materials, and schedule. For a wider view of strategic business performance, connect pricing decisions to the operating model.
Customer- and product-level margin analysis
Revenue alone can hide the workload and costs behind a customer or product. Compare revenue, gross profit, service demands, and contribution before deciding which jobs to accept. The strongest option is not always the one with the highest sales total.
Consider two customers, each generating $100,000 in revenue at a 22.5% gross margin. Customer A places six orders and creates three support tickets annually. Customer B requires 90 orders and 50 tickets for the same revenue and margin, roughly 15 times the workload. That allocation changes the profitability picture.
Calculate customer-level profit by tracing costs that follow each account: order handling, support, delivery, and payment processing. Then compare the resulting contribution with the time and capacity each account consumes. A minute-by-minute workload review can expose repeated service demands that revenue reports miss. Use the results to refine account pricing or service terms, rather than treating every customer alike.
Apply the same approach to products. Start with the selling price, then subtract variable costs such as product costs, freight, and fulfillment fees. Compare each product’s contribution with its target margin and the work required to sell and support it. This shows which products strengthen your pricing strategy and which may need repricing, a different sales approach, or reconsideration.
Segmenting the results helps convert margin analysis into decisions: prioritize profitable work, adjust pricing where costs are misaligned, and avoid accepting volume that strains capacity without adequate return. Strengthen your customer and product profitability analysis by connecting these findings to business performance.
Significant Business Results: Solves the problems of low margins, inconsistent revenue and pressure to lower prices.
Significant Business Results helps architecture, engineering, and construction business owners address low margins, inconsistent revenue, and pressure to lower prices. If project-level analysis reveals a recurring pattern rather than an isolated bid issue, the next step is to strengthen the operating model behind pricing, delivery, and growth.
The goal is practical: improve revenue, performance, and long-term business value while improving operational efficiency and reducing risk. For owners who want the business to run without depending on them every day, this also means building stronger systems and greater organizational independence.
When margin pressure is affecting decisions across the business, contact Significant Business Results to discuss a strategic path forward.
Make Your Next Commitment Strengthen the Business
If your construction business is busier than ever but earning less, make the margin floor a decision rule, not an aspiration. Apply it consistently as opportunities, customer demands, and operating conditions change. The aim is not simply to win more work, but to build a business where sound project economics support lasting performance.
Significant Business Results works with architecture, engineering, and construction business owners to improve revenue, performance, and long-term value while strengthening operational efficiency and reducing risk. This strategic work can also help owners build a business that runs without depending on them for every decision.
Choose a clear next step for your business. Contact Significant Business Results to discuss how to move forward with greater focus and confidence.
Frequently Asked Questions
Do top-performing shops just charge higher labor rates?
No. Paar Melis’s benchmark report found that top- and bottom-performing auto repair shops charged nearly the same labor rate, around $165 per hour. That comparison suggests labor pricing alone doesn’t explain performance differences. Operational efficiency, effective labor utilization, parts profitability, and control of overhead can also affect what remains from each sale. Review the full operating model, not just the posted rate.
Is a 50% markup the same as a 50% margin?
No. Markup measures the amount added to cost; margin measures gross profit as a share of selling price. For example, a 50% markup on a $100 part creates a $150 selling price. The $50 gross profit is 33.3% of that selling price, not 50%. Keep the two calculations separate in estimates and pricing tools to avoid setting prices below the intended margin.
What does “set a margin floor before you sign” mean for service businesses?
A margin floor is the lowest acceptable margin for a job, set before you commit to its scope, price, and terms. It should reflect direct delivery costs, overhead, and profit requirements. For a service firm, it also helps you assess whether revisions, extra coordination, or payment conditions could make an apparently attractive engagement less valuable after signing.
How do you calculate gross profit margin and minimum acceptable job price?
Subtract direct costs from revenue to calculate gross profit, then divide gross profit by revenue to calculate gross margin. To price for a target gross margin, divide direct job costs by one minus the target margin expressed as a decimal. Include all relevant direct costs, then make sure the target margin also supports overhead and required operating profit.
What is a healthy gross margin by industry for contractors and service businesses?
There is no single healthy gross margin for all contractors and service businesses. Project type, labor mix, subcontracting, and overhead structure all influence a viable target. Compare businesses with similar work and cost structures, then set a target that covers your operating needs and profit goals. An industry average can offer context, but it should not replace your company’s own economics.
Article by
Franne McNeal
Franne McNeal, President, Significant Business Results LLC is known for helping architecture, engineering and construction firms with $1M-$20M in annual revenue, build scalable, transferable companies that increase in value, reduce owner dependence, and create more options for growth, succession, or sale. She help architects, engineers and construction firms become more valuable, so they don't collapse when the owner steps back. She solves the problems of low margins, inconsistent revenue and pressure to lower prices, by helping clients create a business that is an asset (one that runs without them), based on a proven system 8-pillar framework to increase the value of a business by 71%. Her clients are empowered to move from being indispensable operators to intentional builders of enduring businesses, so they create financial & personal freedom. Franne "FranneTastic" McNeal has helped 886+ small business owners collectively create 15,000 jobs and nearly $11 billion in revenue. She helps clients focus their energy for action to achieve significant business results.