
From Owner-Bonded to Company-Bonded
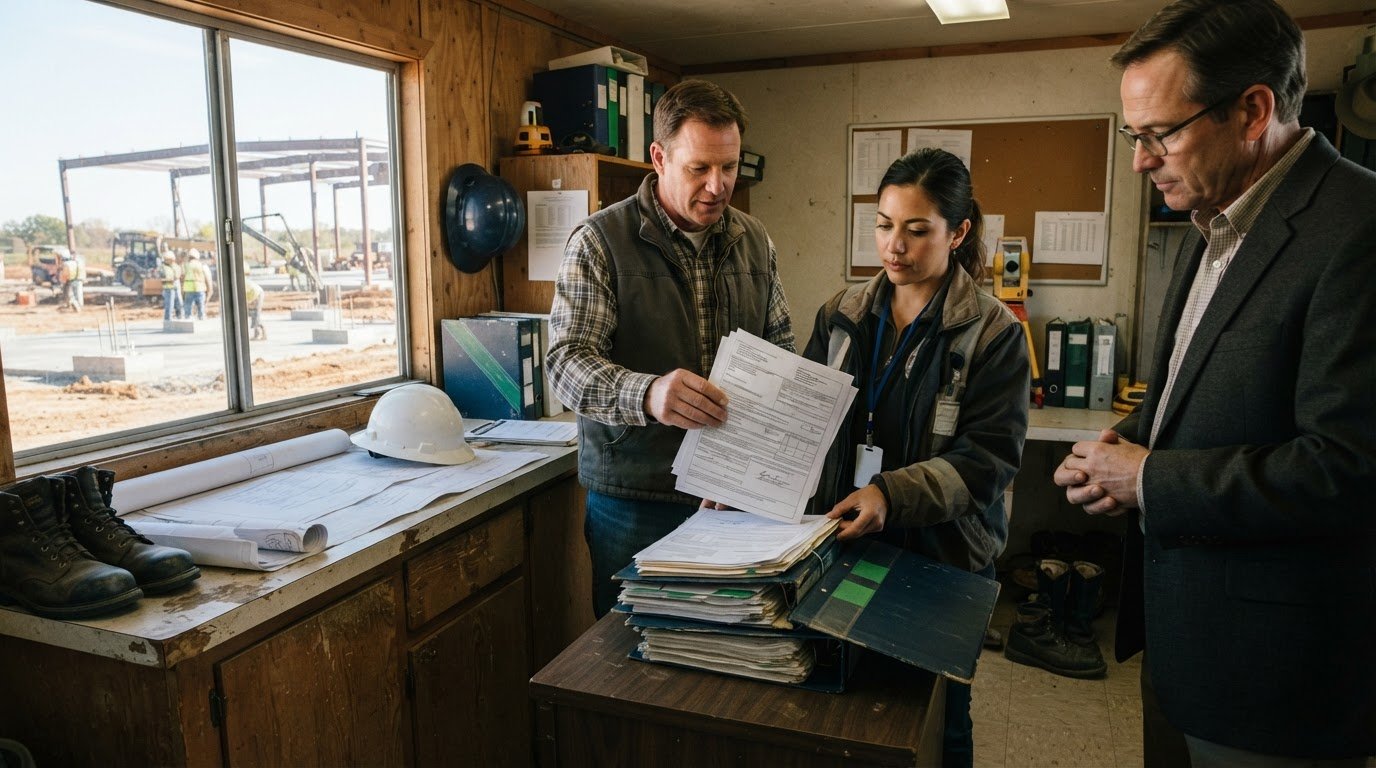
The legal entity named on a bond matters. Moving from owner-bonded to company-bonded means naming the business entity, rather than the individual owner, as the principal. The bond still backs an obligation owed to the party requiring it. In a surety bond, the surety issues the bond, the obligee requires it, and the principal purchases it. If the surety pays a claim on the business’s behalf, the business must reimburse the surety for the amount paid.
This may look like a simple administrative update, but the bond and its indemnity obligations have practical consequences for the owner and company. A surety bond protects a third party; insurance protects the insured business. This article explains what being bonded means, what changes when the company becomes the principal, and how an independent insurance broker can help identify a bond suited to the company’s obligations.
Key Takeaways
• Understand what changes when a bond names the company rather than its owner as the principal.
• See why the bond’s named principal matters to the business and the owner’s responsibilities.
• Learn how bond obligations differ from insurance protection and why the distinction matters.
• Identify how an independent insurance broker can help match a business bond to the company’s requirements.
Table of Contents
• What does changing from owner-bonded to company-bonded mean?
• What is the difference between owner-bonded and company-bonded status?
• Significant Business Results
What does changing from owner-bonded to company-bonded mean?
A surety bond has three parties: the surety that issues it, the obligee that requires it, and the principal that purchases it. The principal is the party whose obligation the bond supports. In an owner-bonded arrangement, that principal is the individual owner. In a company-bonded arrangement, the principal is the business entity, such as a corporation or limited liability company.
That distinction affects how the bond relates to the business’s contractual or regulatory obligations. For example, if a construction contract requires a performance bond, naming the company as principal aligns the bond with the entity responsible for the work. The owner’s personal involvement does not, by itself, make the owner and company the same principal.
Moving from owner-bonded to company-bonded means updating the bond arrangement to identify the company as principal. The surety and obligee remain distinct parties, and the bond still secures the underlying obligation. The named principal changes, so the bond documents, business entity, and contract or requirement should align.
It is also important to understand the indemnity obligation. If a surety pays a valid claim on the principal’s behalf, the principal must reimburse it for the amount paid. A company named as principal may be assessed based on its financials and experience, while the owner may still have responsibilities under an indemnity agreement. The agreement’s signatories determine who has agreed to reimburse the surety.
Mechanic’s lien bonds illustrate why location and bond purpose matter. In New York, a bond to indemnify a mechanic’s lien must equal 110% of the lien claim, according to the New York State Senate. In California, a contractor must file suit to enforce a mechanic’s lien within 90 days of recording the lien, regardless of when the bond is posted, according to the California Legislature. Those rules concern lien bonds and enforcement, not every type of business bond.
For a company making this transition, such as clients working with Significant Business Results, focus on consistency: identify the legal entity responsible for the obligation, clarify who will sign the indemnity agreement, and coordinate the bond documents with the surety and obligee. A freight broker, for example, has different bond requirements from a construction contractor. The bond type and named principal must suit the business activity and the requirement being met.
A performance bond or indemnity bond protects the obligee regarding the obligation being secured. A performance bond or indemnity bond can protect a customer against loss if a business fails to meet its obligations. Surety bonds can help protect clients when a business does not meet its obligations.
A business seeking a bond can consult an independent insurance broker to identify the bond it needs. This can help determine the type of bond and principal that fit the obligation.
What is the difference between owner-bonded and company-bonded status?
The key difference is who is named as principal. In an owner-bonded arrangement, the individual owner is named. In a company-bonded arrangement, the business entity is named instead. For a contractor operating through a corporation, this determines whether the bond identifies the owner or the corporation as the party whose obligation is secured.
The distinction can also affect how the surety assesses the application. A surety may review business experience, references, financial statements, personal credit, and access to bank credit. A company-bonded application centers on the company’s business profile, but personal credit and financial backing may still be part of the review. Naming the company on the bond does not automatically make the owner’s finances irrelevant.
Indemnity terms matter, too. A company may be named as principal while the owner also signs an indemnity agreement. If the surety pays a claim, the agreement determines who has undertaken to reimburse it. The bond and indemnity agreement serve different purposes, so changing the principal does not, by itself, end a personal commitment already made.
Consider an engineering firm that changes from an individual practice to a limited liability company. If a client’s bond requirement identifies the firm as the responsible contracting party, a bond naming only the owner may not match. The bond, contract, and legal business identity should align, helping clients and contracting partners understand which entity is tied to the obligation.
The transition can also affect how the company organizes its bond records. Naming the company as principal connects the bond with company contracts, financial statements, and operating history. This can make the bond relationship easier to manage as the business takes on work or changes structure. It does not change the bond’s purpose or guarantee that a claim will not arise.
Before making a change, consider the relevant parties and documents together:
Principal
Identify whether the owner or the business entity is named.
Obligation
Match the bond to the company or individual responsible under the contract or requirement.
Indemnity
Understand which parties have agreed to reimburse the surety.
Financial review
Prepare for scrutiny of business financials, experience, and personal credit.
Company-bonded status names the business as principal. It does not automatically transfer every responsibility from the owner: the contract, bond, and indemnity agreement each define different obligations.
Significant Business Results
Significant Business Results helps architecture, engineering, and construction business owners improve operational efficiency and reduce risk across their companies. Bonding decisions sit within a broader picture of business structure, contract obligations, and risk management. For owners managing growth or changing how the company operates, aligning responsibilities and strengthening business performance can support more durable operations.
Turn to Significant Business Results when a transition raises broader questions about how the company operates, where operational risks lie, or how to build an organization less dependent on its owner. The firm helps improve business performance and long-term value; it does not replace bond-specific guidance from an independent insurance broker.
Contact Significant Business Results to discuss your company’s operational priorities.
Make the Next Business Decision Deliberately
As your company evolves, treat the move from owner-bonded to company-bonded as part of a broader effort to align responsibilities, operations, and long-term direction. The bond addresses a specific obligation, while the business structure around it affects how confidently the company can take on work and grow. For architecture, engineering, and construction owners, stronger operations can support day-to-day performance and lasting business value.
Significant Business Results helps owners improve revenue, performance, and long-term value, reduce operational risk, and build businesses that can run without them. This broader perspective can help when a bonding change raises questions about company systems, resilience, or future growth. Take the next step with a focused conversation about your priorities and where you want the business to go.
Contact Significant Business Results to discuss your company’s next stage with clarity and confidence.
Frequently Asked Questions
Can a company assume an owner's existing bond, or must it obtain a new bond?
Update the bond arrangement to name the company as principal and align the bond documents with the business entity and underlying obligation. Coordinate the change with the surety and obligee. An existing bond cannot necessarily be assumed, and a new bond is not always required.
What are the steps and typical timeline for changing from owner-bonded to company-bonded?
Identify the entity responsible for the obligation, clarify who will sign the indemnity agreement, and coordinate the bond documents with the surety and obligee to ensure they align with the contract or requirement.
Article by
Franne McNeal
Franne McNeal, President, Significant Business Results LLC is known for helping architecture, engineering and construction firms with $1M-$20M in annual revenue, build scalable, transferable companies that increase in value, reduce owner dependence, and create more options for growth, succession, or sale. She help architects, engineers and construction firms become more valuable, so they don't collapse when the owner steps back. She solves the problems of low margins, inconsistent revenue and pressure to lower prices, by helping clients create a business that is an asset (one that runs without them), based on a proven system 8-pillar framework to increase the value of a business by 71%. Her clients are empowered to move from being indispensable operators to intentional builders of enduring businesses, so they create financial & personal freedom. Franne "FranneTastic" McNeal has helped 886+ small business owners collectively create 15,000 jobs and nearly $11 billion in revenue. She helps clients focus their energy for action to achieve significant business results.